- Free Consultation: (925) 266-3449 Tap Here To Call Us
Can a Trust Protect Assets from Nursing Home Costs?


A trust can be part of a plan to protect assets from nursing home costs, but the type of trust—and when it is created—matters. A standard revocable living trust generally does not provide this protection.
Why a Revocable Living Trust Is Not Enough
A revocable living trust helps avoid probate, manage assets during incapacity, and direct property after death. However, the person who creates the trust usually retains the right to amend or revoke it and continues to control its assets. Because those assets remain available to the trust creator, transferring a home or savings into a revocable living trust ordinarily does not shelter them when determining responsibility for long-term care expenses or eligibility for needs-based benefits such as Medi-Cal.
Clients concerned about nursing home costs may need to consider additional planning tools.
Trusts That May Help
Irrevocable Asset-Protection Trust
An irrevocable trust designed for long-term-care planning may remove assets from the person’s ownership and control. Depending on its terms, the trust might hold a residence, investments, or other property for designated beneficiaries.
This strategy requires the creator to surrender meaningful control. The trust generally cannot function as an asset-protection tool if the creator can freely revoke it or reclaim the principal. Transfers may also affect Medi-Cal eligibility, particularly if they occur during an applicable look-back period.
Advance planning is therefore critical. Creating or funding an irrevocable trust immediately before nursing home admission may be too late to accomplish the intended goal.
Income-Only Trust
An income-only trust is a form of irrevocable trust that may permit the creator to receive income generated by trust property while preventing access to the principal. For example, the trust might hold an investment account and distribute its earnings, while preserving the underlying assets for children or other beneficiaries.
Receiving trust income can still affect Medi-Cal eligibility or the amount the beneficiary must contribute toward care. The trust must be drafted and administered carefully so that retained rights do not defeat the plan.
Special Needs Trust
A special needs trust may benefit a person with a disability without giving that person unrestricted control over trust assets. It can supplement—not replace—certain public benefits by paying for permitted goods and services.
Different rules apply depending on whether the trust is funded with the beneficiary’s own property or with assets belonging to someone else. Some trusts funded with the beneficiary’s assets must contain repayment provisions for benefits received. A third-party special needs trust, often created by a parent or other relative, can provide greater flexibility and may avoid that repayment requirement.
Testamentary Trust
A testamentary trust is created under a will and takes effect at death. It may be useful when one spouse wants to provide for a surviving spouse while limiting the survivor’s direct ownership or control of inherited assets.
This trust does not protect the assets of the person who created the will during that person’s lifetime. Instead, it can help structure an inheritance for a surviving spouse who may later need long-term care.
Practical Planning Tips
1. Plan early. Transfers to irrevocable trusts can create periods of ineligibility or other unintended consequences.
2. Do not transfer every asset. Retaining sufficient funds for housing, living expenses, taxes, and emergencies is essential.
3. Choose the trustee carefully. An irrevocable trust may place substantial authority in the trustee’s hands.
4. Coordinate the entire estate plan. Trusts should work with beneficiary designations, powers of attorney, health care directives, and the plan for the home.
5. Consider tax consequences. A transfer that helps with long-term care planning may affect capital gains treatment, property taxes, or estate administration.
6. Review the plan regularly. California Medi-Cal eligibility and estate recovery rules can change. A strategy based on outdated limits or transfer rules may not work as intended.
The Bottom Line
A revocable living trust is valuable, but it ordinarily does not protect assets from nursing home costs. An appropriately designed irrevocable trust, income-only trust, special needs trust, or testamentary trust may address concerns that a revocable trust cannot. The right approach depends on the client’s assets, family circumstances, timing, and willingness to give up control.
If you want to speak with an attorney about estate planning, reach out to Fidelitas Law at (925) 266-3449 or info@fidelitaslaw.com.
Address
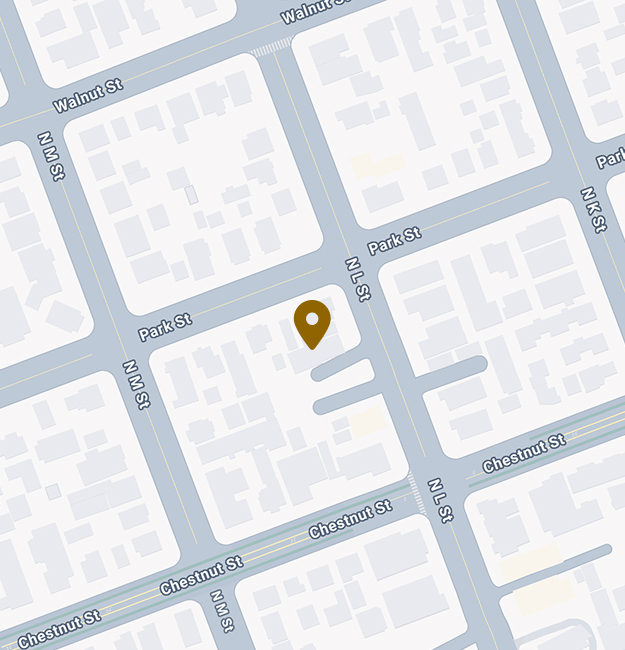
Our office is in downtown Livermore — next door to an antique store and surrounded by historic hills and vineyards. Email us at info@fidelitaslaw.com.